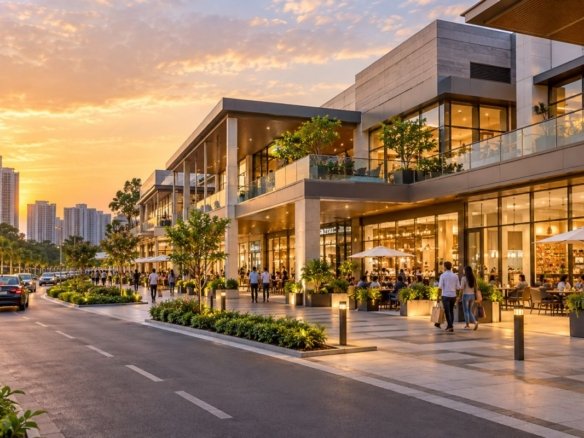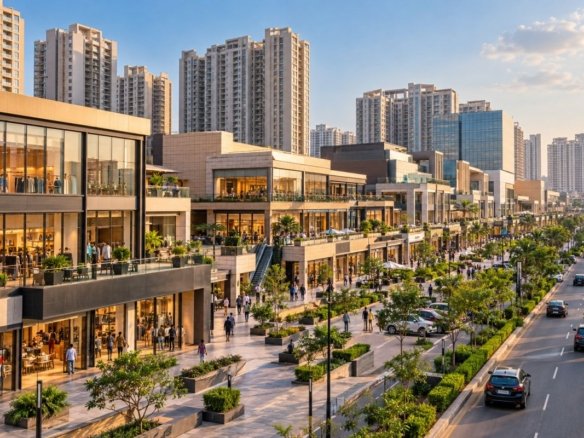
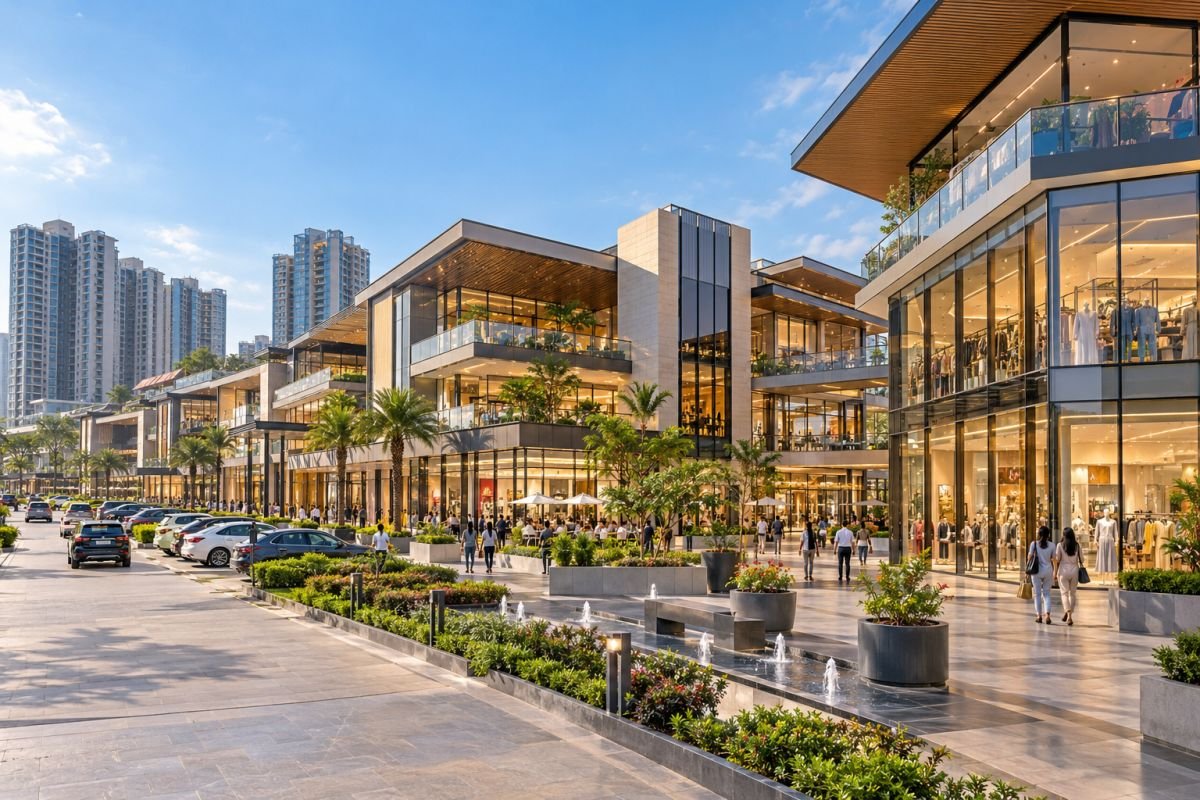
Elan Miracle Sector 84 Gurgaon occupies a commercial position that warrants analysis beyond its advertised retail format. Located in Sector 84 along the Dwarka Expressway corridor, the development combines high-street retail with food, entertainment and other commercial uses. The investment question is whether its surrounding residential demand translates into repeat customer visits, sustainable tenant sales and sufficient rent to justify the acquisition price.
For commercial real estate investors, retail leasing heads and high-net-worth individuals, the distinction matters. A prominent location does not automatically produce profitable retail space. Floor visibility, the tenant’s business model, access, internal circulation, occupancy in neighbouring residential towers and the cost of holding a vacant unit can materially change the investment outcome.
This Elan Miracle Sector 84 Gurgaon review evaluates the project through five lenses: residential catchment, footfall drivers, floor-wise leasing efficiency, net rental yield and regulatory due diligence. It separates published project information from market evidence that still requires verification.
Elan Miracle Sector 84 Gurgaon Commercial Overview: Format, Builder & Sector Positioning
Elan Miracle is a commercial development by Elan Buildcon Private Limited. The developer’s disclosure identifies the project as a high-street retail and entertainment destination, with retail shops, food courts, a multiplex, landscaped common areas and associated commercial spaces. The official project material also describes its position along a 150-metre-wide Dwarka Expressway corridor and highlights its three-side-open configuration. These are project-design and positioning claims; the commercial advantage of each feature depends on the individual unit’s visibility and access.
The official disclosure records a licensed land area of 23,952.33 square metres, equivalent to approximately 5.92 acres. This is the appropriate reference for the licensed land area rather than relying on rounded third-party marketing descriptions.
| Project factor | Verified or qualified position |
|---|---|
| Project | Elan Miracle |
| Location | Sector 84, Gurugram, Haryana |
| Developer entity | Elan Buildcon Private Limited |
| Licensed land area | Approximately 5.92 acres |
| Commercial format | High-street retail, food and entertainment uses |
| HRERA registration | No. 190 of 2017 |
| Published OC reference | Dated 15 March 2023; underlying certificate and scope require inspection |
| Current unit-level pricing | Requires dated inventory and quotation verification |
| Actual leasing performance | Requires executed lease and occupancy evidence |
The project should be evaluated as a multi-format retail destination, not as a uniform collection of interchangeable shops. A ground-floor unit facing a strong customer approach may have a different tenant pool from an upper-floor unit that depends on escalators, lifts, destination shopping or food-and-entertainment traffic.
Investors should also distinguish the project’s mall-style shared circulation from independent street-facing commercial property. Both can benefit from a strong residential market, but their visibility, operating costs, tenant mix and leasing dynamics differ. The high-street vs mall retail investment guide in Gurgaon provides a useful framework for comparing these formats.
3-Km Residential Catchment & Daily Footfall Drivers in Sector 84
A three-kilometre catchment is a useful starting point for evaluating convenience retail, food and beverage, personal services and neighbourhood shopping. It is not, by itself, a reliable estimate of customers or household spending.

The relevant catchment for Elan Miracle includes residential communities in and around Sector 84, along with nearby parts of New Gurgaon. However, a defensible population estimate must count occupied homes rather than simply adding the total units advertised across nearby projects.
Three groups should be separated:
- Delivered and occupied apartments: The most immediately relevant residential demand, subject to actual occupancy and household spending.
- Delivered but partly occupied apartments: A potential source of future customers, but not equivalent to an established customer base.
- Near-possession developments: A future demand factor whose timing depends on actual completion, handover and resident move-in.
For a measured 3-km catchment, the analyst should map the project entrance, draw a three-kilometre radius and identify residential buildings within that boundary. Each building should then be classified by delivery status, occupancy, unit count and access route. A separate drive-time or walking-access analysis is valuable because a geometric radius does not account for road crossings, barriers or indirect entrances.
What can generate daily footfall?
Elan Miracle’s mixed retail and entertainment format provides several possible demand channels:
- Convenience shopping: Grocery, pharmacy, personal care and everyday services can generate repeat visits from nearby households.
- Food and beverage: Cafés, restaurants and casual dining can capture evening and weekend demand, provided tenant pricing and accessibility match the local market.
- Entertainment-led visits: The developer advertises a multiplex and leisure-oriented spaces. Their contribution depends on operational status, programming, customer traffic and the performance of complementary tenants.
 Elan Official Website+1
- Destination retail: Specialist retail and higher-ticket brands can draw customers from beyond the immediate catchment, but generally require stronger brand pull and customer acquisition.
These channels are not interchangeable. A cinema visitor does not necessarily purchase from every retail tenant, and event-driven weekend footfall cannot be treated as stable weekday demand.
How to assess road frontage and visibility
The project’s expressway-side positioning is a locational advantage, but visibility must be tested at unit level. Investors should inspect the direction of approach, the distance between the carriageway and shop entrance, signage permissions, parking access, drop-off facilities, pedestrian connections and the visibility of the actual retail frontage.
A shop visible from a road may still be difficult to enter. Conversely, an internal unit can work when it is near an active anchor, food court, escalator or entertainment entrance.
For a credible footfall study, count pedestrians at the principal entrances and relevant internal circulation points during weekday mornings, weekday evenings and weekend peak periods. Record the count interval, weather, operating tenants and any events. Until that work is completed, the project’s exact 3-km population and daily footfall should be treated as unverified, not stated as a numerical fact.
For a broader view of the area, review the commercial and residential catchment in Sector 84.
Floor-Wise Layout Analysis: Ground-Floor Frontage vs Upper-Floor Zoning
The right floor depends on the intended tenant, the unit’s position and the difference between acquisition cost and achievable rent. A blanket assumption that the ground floor is always the best investment ignores capital intensity and tenant suitability.
| Unit position | Likely tenant fit | Leasing advantages | Key risks |
|---|---|---|---|
| Lower-ground floor | Selected value retail, supermarket or destination uses | Can suit larger formats where access and circulation work | Weaker natural visibility, dependence on vertical circulation and access |
| Ground floor | Convenience retail, branded stores, selected F&B and service businesses | Stronger potential for walk-in discovery and direct frontage | Higher acquisition cost can reduce yield |
| First floor | Restaurants, lifestyle retail, service-led businesses | Can work near escalators, anchors and food clusters | Depends on signage, vertical circulation and destination demand |
| Upper floors | Destination dining, entertainment-related or selected commercial uses | Potentially lower entry cost, depending on unit and floor | Narrower tenant pool and potentially longer vacancy periods |

This is a functional assessment, not a verified schedule of the project’s individual floor plates or tenant allocation. The approved floor plans and actual operating layout must be checked before assigning a unit to any category.
Ground-floor frontage: liquidity versus capital cost
Ground-floor units generally have an advantage when the business relies on spontaneous visits, street-level visibility or immediate access. Their leasing liquidity may also be better when multiple tenant categories can use the space without major structural modifications.
However, the premium paid for a ground-floor unit is justified only if the additional rent or resale demand compensates for the higher investment. A unit purchased at a substantial premium can produce a lower percentage yield than an upper-floor alternative, even when it commands a higher monthly rent.
Upper-floor zoning: tenant fit matters
Upper-floor retail can work for destination businesses that customers deliberately seek out. Restaurants, specialist retail and service-led businesses may be less dependent on passing traffic than convenience shops.
The investor should inspect the route from the entrance to the unit, the position of escalators and lifts, directional signage, permitted operating hours, exhaust and utility provisions for F&B, and the relationship with nearby anchors.
Before purchase, obtain the approved floor plan, unit number, sanctioned use, carpet area, super area and common-area allocation. Confirm whether the quoted price is based on carpet area or super area and whether the sale deed uses the same measurement basis.
Investment implication: Ground-floor frontage is often the stronger starting point for walk-in retail liquidity, but the best risk-adjusted investment is the unit whose rent potential, purchase price and vacancy exposure produce the strongest net outcome.
2026 Capital Values, Lease Rental Benchmarks & Net Yield Math
The central question in the Elan Miracle Sector 84 Gurgaon rental yield analysis is whether the rent available for a specific unit adequately compensates for its purchase price, recurring expenses and vacancy risk.

Current online listings provide useful preliminary evidence, but not a definitive valuation. For example, a NoBroker listing published in August 2026 advertised a 676 sq. ft. shop at ₹85,000 per month, equivalent to approximately ₹126 per sq. ft. per month. Another listing advertised a 236 sq. ft. shop at ₹25,000 per month, or approximately ₹106 per sq. ft. per month, with separately stated maintenance charges. These are asking rents, not confirmed executed lease rates.
The difference between the two advertised rates is a reminder that floor, frontage, unit size, maintenance treatment and tenant suitability can influence asking rent. A small shop’s rent per square foot should not be applied indiscriminately to a larger unit.
Indicative asking-price and rent evidence
| Metric | Available evidence | Limitation |
|---|---|---|
| Advertised rent | Approximately ₹106–₹126 per sq. ft. per month in two sampled listings | Small sample; not a market-wide average |
| Advertised purchase price | Must be established from current, comparable unit quotations | No sufficiently reliable, matched transaction dataset established |
| Ground-floor premium | Requires same-project, same-area and same-frontage comparisons | Do not assume a fixed premium |
| Upper-floor pricing | Requires dated inventory and unit-specific quotations | Do not extrapolate from other floors |
| Net yield | Must be calculated from the purchase price and actual operating expenses | Cannot be confirmed from asking rent alone |
These figures are a preliminary evidence set, not a recommended rent schedule or valuation opinion. The project’s price list should be verified by floor, unit size, frontage, orientation, total consideration and recurring charges before a buyer makes an offer.
Gross vs Net Rental Yield (Factoring CAM, Property Tax & Fit-Out Periods)
Gross rental yield is the annual rent divided by the total acquisition cost. Net rental yield deducts the expenses borne by the owner, including applicable common-area maintenance (CAM), property tax, vacancy, repairs, leasing costs and other unrecovered charges.
\[ \text{Gross yield}=\frac{\text{Annual rent}}{\text{Total acquisition cost}}\times100 \]
\[ \text{Net yield}=\frac{\text{Annual rent}-\text{Owner expenses}}{\text{Total acquisition cost}}\times100 \]
The denominator should include the purchase consideration and relevant acquisition costs, not just the headline property price. Stamp duty, registration, brokerage, fit-out contributions and other applicable costs can materially reduce the initial return on capital.
The assumptions above are for sensitivity analysis, not confirmed CAM or property-tax rates. Actual charges must come from the property’s invoices and assessment records. The calculation also assumes that one month is lost to vacancy or rent-free time, with no double-counting of that period.
The impact of the acquisition price is substantial:
| Assumed total acquisition cost per sq. ft. | Total cost for 1,000 sq. ft. | Illustrative gross yield | Illustrative net yield |
|---|---|---|---|
| ₹15,000 | ₹1.50 crore | 9.12% | 7.08% |
| ₹20,000 | ₹2.00 crore | 6.84% | 5.31% |
| ₹25,000 | ₹2.50 crore | 5.47% | 4.25% |
These are mathematical scenarios, not verified Elan Miracle capital values or yield forecasts. The acquisition-cost scenarios are assumed, and the model excludes financing, income tax and major capital expenditure.
The lesson is straightforward: a rent that appears attractive in isolation may not justify a high acquisition price. Conversely, a lower-priced unit may still be a poor investment if it faces prolonged vacancy or requires significant tenant incentives.
CAM charges, property tax and lease terms
CAM may include common-area cleaning, security, lift and escalator operations, common electricity, facility management and shared-area maintenance. The actual charge structure depends on the project’s governing documents and billing arrangements.
Investors should obtain the latest CAM invoices, the basis of allocation, any outstanding dues, the treatment of vacant units and the escalation provisions. Property tax should be checked against the relevant assessment and billing records rather than estimated from a generic percentage.
Commercial lease lock-ins are negotiated terms, not a universal Sector 84 standard. The signed lease should clarify the lock-in period, notice period, rent escalation, security deposit, rent-free fit-out period, permitted use, maintenance allocation, taxes, reinstatement obligations and early-termination remedies.
Self-Use Business vs Pure Leasing ROI
The same unit can have different economics for an owner-occupier and a rental investor.
| Consideration | Self-use business | Pure leasing investor |
|---|---|---|
| Primary return | Business operating profit and avoided rent | Rental income and capital value change |
| Critical location factor | Customer access, visibility and suitability | Tenant demand and achievable rent |
| Vacancy exposure | Not applicable in the same way, but business underperformance remains a risk | Directly affects rental income |
| Fit-out | Designed around the owner’s business | Often negotiated with the tenant |
| Liquidity | Depends on suitability for a future buyer | Depends on income profile, lease quality and unit demand |
For a retailer, the relevant question is whether the location supports sufficient sales to cover rent, staffing, inventory, utilities and other operating costs. A prime frontage may be justified if it improves customer acquisition and sales conversion.
For a leasing investor, the focus is different: the achievable rent, tenant covenant, lease duration, recurring expenses and probability of reletting. A signed lease should be independently reviewed, particularly if the investment is being marketed as pre-leased.
Neither case should rely on an assumed guaranteed return. Investors should stress-test lower rents, a longer vacancy period, tenant turnover and additional capital expenditure before deciding what price to pay.
HRERA Compliance, Completion Timeline & Vacancy Risk Assessment
The official Haryana RERA record identifies Elan Miracle under registration number 190 of 2017, dated 14 September 2017. The developer’s published disclosure also cites an Occupancy Certificate dated 15 March 2023. These references provide a starting point for due diligence, but they do not establish that every unit has identical approvals, handover conditions or legal status.

For an existing commercial asset, the buyer should focus on the legal status of the exact unit and its operating environment rather than relying exclusively on project-level marketing claims.
HRERA and OC verification checklist
Before paying a booking amount or executing a transfer, obtain and review:
- HRERA record: Registration certificate, project details, amendments and relevant orders or complaints.
- Approved building plans: Confirm the sanctioned use, floor, unit location, circulation and relevant common areas.
- Occupancy Certificate: Obtain the authority-issued OC and confirm that the relevant building, block and area are covered.
- Title and transfer documents: Verify the title chain, conveyance deed or applicable transfer documentation, encumbrances, mortgages and the seller’s authority to transfer.
- Unit-specific documents: Allotment letter, agreement for sale, possession letter, sale deed, unit area statement and any subsequent area adjustment.
- Financial dues: CAM statements, property-tax bills, electricity and other utility dues, and any outstanding payments to the developer or association.
- Lease documentation: Existing lease, tenant identity, security deposit, lock-in, escalation, termination rights, rent receipts and any rent-free or fit-out commitments.
- Dispute checks: Search relevant HRERA orders and complaints, and verify whether any litigation, charge or other restriction affects the unit.
The project also appears in HRERA complaint records relating to commercial-unit matters, including issues concerning possession and fit-out possession or super-area changes. These entries warrant document-level review; they do not, by themselves, establish that every unit is affected or that the entire development is non-compliant.
Vacancy risk: the cost investors often underestimate
A retail unit can remain vacant even in a growing residential corridor. Vacancy risk rises when the rent required by the owner exceeds what a tenant’s business can support, when the unit is poorly visible, or when the tenant mix fails to generate repeat visits.
The following factors deserve particular attention:
- Tenant affordability: Does the expected sales turnover support rent, CAM, staffing and operating costs?
- Anchor performance: Are the relevant food, entertainment and retail components operational and attracting repeat visits?
- Unit accessibility: Can customers find and enter the unit without friction?
- Tenant concentration: Does the asset depend heavily on one anchor or a narrow category of tenants?
- Reletting costs: How much rent-free time, brokerage, refurbishment and compliance work might a replacement tenant require?
- Exit liquidity: Would another investor buy the unit based on documented income, or only on projected appreciation?
A delivered project reduces construction-completion uncertainty relative to an unfinished asset, but it does not eliminate leasing, title, operating or resale risk. The investment case must be supported by current evidence of how the actual unit performs.
Final Verdict: Who Should Invest in Elan Miracle Sector 84 Gurgaon?
Elan Miracle deserves consideration from investors seeking commercial retail exposure in New Gurgaon, particularly those who understand the relationship between residential demand, retail accessibility and tenant economics. Its high-street retail and entertainment format offers several potential demand channels, while its location along the Dwarka Expressway corridor provides a clear geographic proposition. Neither factor, however, proves that a particular unit will achieve a specific rental yield.
The strongest investment case is likely to come from a unit with demonstrable visibility, practical access, a suitable tenant profile and an acquisition price supported by achievable rent. Ground-floor frontage can be attractive for walk-in retail, while upper-floor units may be worth considering where destination demand and the purchase-price discount justify the additional leasing risk.
Investor decision matrix
Potentially suitable
Investors with a medium- to long-term holding horizon, sufficient vacancy reserves and a willingness to verify unit-level leasing economics before purchasing.
Retail brands and owner-occupiers
Businesses that have assessed the customer catchment, access, frontage, operating costs and expected sales required to sustain the location.
Proceed cautiously
Buyers depending on immediate rental income, borrowed-capital returns, unverified pre-leasing claims or rapid resale appreciation.
The final decision should depend on three documents: a verified unit-level price quotation, a realistic rental assessment supported by comparable leases, and a complete legal and operating-cost review.
For unit-specific information, review the Elan Miracle Sector 84 Gurgaon commercial price list and layout. Ask for the latest available inventory, floor plans, area statement and commercial terms rather than relying on an undated price indication.
Frequently Asked Questions
1. What is the realistic rental yield and lease potential of Elan Miracle Sector 84 Gurgaon in 2026?
Available online advertisements provide preliminary asking-rent evidence of approximately ₹106–₹126 per sq. ft. per month for selected units. These are not verified achieved rents or a representative market average.
Realistic rental yield depends on the negotiated rent, total acquisition cost, owner-borne CAM, property tax, vacancy and leasing expenses. The illustrative model in this review demonstrates how net yield can differ substantially from gross yield. Investors should obtain comparable executed leases and a unit-specific quotation before adopting a yield assumption.
2. How large is the residential catchment surrounding Elan Miracle Sector 84 Gurgaon?
A three-kilometre radius is a useful initial study area, but the number of residents and households within it has not been independently established here. A defensible estimate requires mapping delivered residential buildings, verifying occupied units, separating near-possession developments and checking actual access routes.
The number of apartments marketed within a radius should not be treated as the number of occupied homes or regular retail customers.
3. Which floor or unit type offers the best capital appreciation and leasing liquidity at Elan Miracle Sector 84 Gurgaon?
Ground-floor units with strong frontage and accessible entrances can have advantages for convenience retail and spontaneous customer visits. Upper-floor units can suit destination-led businesses where vertical circulation, signage and anchor proximity are effective.
The best investment is not necessarily the floor with the highest price or rent. Compare acquisition cost per sq. ft., achieved rent, tenant demand, vacancy duration and resale evidence for comparable units. No floor-specific appreciation premium has been independently verified for this review.
4. What are the CAM charges, property tax and lock-in norms for commercial units in Sector 84?
There is no single verified CAM rate, property-tax figure or universal lease lock-in applicable to every commercial unit in Sector 84.
Request the latest CAM invoice and allocation basis, the relevant property-tax assessment and payment records, and the draft or executed lease. Confirm the lock-in, notice period, rent escalation, security deposit, fit-out period, permitted use and expense allocation in writing. The illustrative cost assumptions in this article should not be used as actual project charges.
5. What HRERA and OC documents should investors check before buying in Elan Miracle Sector 84 Gurgaon?
Start with HRERA registration No. 190 of 2017 and the developer’s published OC reference dated 15 March 2023. Verify the underlying documents against the authority’s records.
Also inspect approved building plans, title and transfer documents, unit-specific area statements, possession documentation, outstanding dues, encumbrances, applicable approvals and any relevant HRERA orders or complaints. Where the unit is leased, independently verify the tenant, rent receipts, lease terms and termination provisions.